Door categorieën bladeren
Ontdekken
Fiverr Pro
Nederlands
$
USD
Your servicer says the loan paid off. Did it?
If you buy loans from originating partners, remittance files arrive every month and almost nobody re-derives the math. Balances drift. Payoffs get reported that never paid off. A loan goes delinquent in one file and current in the next.
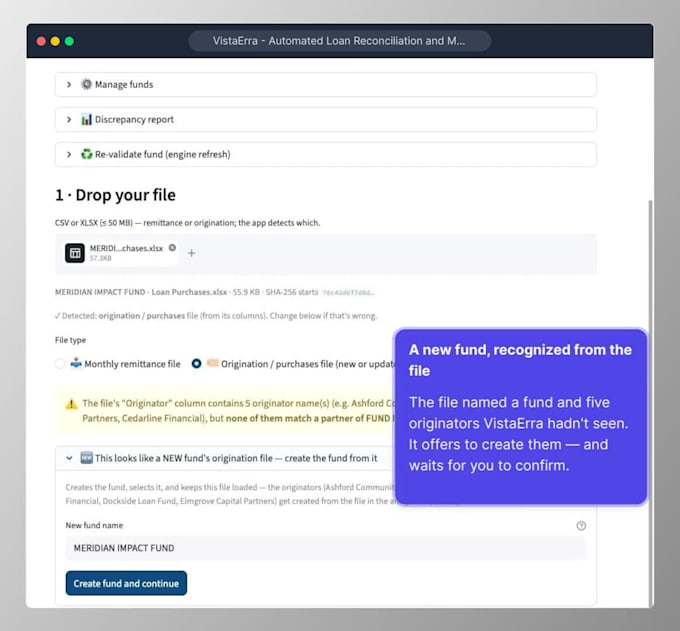
I rebuild your portfolio's history from your own files and check every loan, every month:
- Beginning balance minus principal equals ending balance
- Cumulative principal against the origination amount
- Payoffs that actually cover the outstanding balance
- Delinquency status transitions that make sense
- Loans missing from a file entirely
Every failure becomes a documented discrepancy - by originator, by loan, by month - with the arithmetic shown and sorted by severity. You get it in Excel with a summary of what to ask your servicer.
I spent my career in fund finance doing this by hand, then built an engine so it takes minutes: 18 months and ~11,000 payment rows in one pass. In testing it caught a loan marked PAID OFF with $27,829 still outstanding.
No borrower PII required - loan IDs and dollar amounts only. NDA welcome.
Message me your file layout and I'll tell you if it's a fit.


How is this different from what my servicer reports?
Your servicer reports what they believe happened. I re-derive it independently from the payment data and flag every place the two disagree. In testing that surfaced a loan marked PAID OFF with $27,829 still outstanding.
What size portfolio can you handle?
Tens of thousands of payment rows across dozens of originators. For scale: 800 loans, 5 originators, 18 months and about 11,000 payment rows reconcile in a single pass.
My files are messy. Is that a problem?
Expected. Every servicer names columns differently and I map yours. Rows that fail validation are reported rather than silently dropped, so you always know what wasn't counted and why.
Do you need borrower personal information?
No, and please don't send it. I work from loan IDs, dates, dollar amounts and status codes only. That keeps consumer data out of the engagement entirely.
What happens to my data?
Held in an encrypted workspace for the engagement and deleted on delivery at your request. Happy to sign your NDA before you send anything.
Will you only find errors in my favor?
No. You get everything I find, in both directions. Some findings are money owed back to you, others are your own records being wrong. An honest reconciliation reports both.
Can I get this every month?
Yes. Premium includes three monthly closes after the initial reconciliation, and further months are available as an extra. Most clients start with history, then stay for the close.
Can you add checks specific to my portfolio?
Often yes. Custom tolerance thresholds, per-originator rules, fee handling and charge-off timing policies are all configurable. Tell me the rule you apply manually today and I'll tell you if it's in scope and what it costs.
My portfolio is bigger than these packages. What would it cost?
Send me your loan count, originator count and months of history and I'll come back with a fixed-price offer, usually same day. Size affects my review time, not the engine — verification is what I'm pricing.
Can we run the software ourselves instead?
Yes. VistaErra is available as software your team runs, with your data in its own isolated database and role-based logins. Setup is per customer rather than an instant order, so message me here and we'll work out which fits you better.