Door categorieën bladeren
Ontdekken
Fiverr Pro
Nederlands
$
USD
Quant engineer, I stress test and upgrade trading strategies
Parameter sweeps find the settings that fit the past best. That is not a bug in your process it is the definition of curve-fitting, and it is why optimized strategies stop working.
What you get
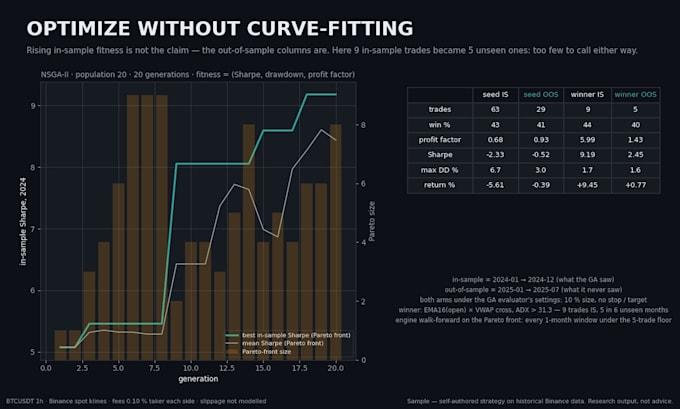
Genetic-algorithm search over your parameters, scored on walk-forward OUT-OF-SAMPLE windows never on in-sample profit
Risk constraints inside the fitness function: max drawdown, exposure, minimum trade count
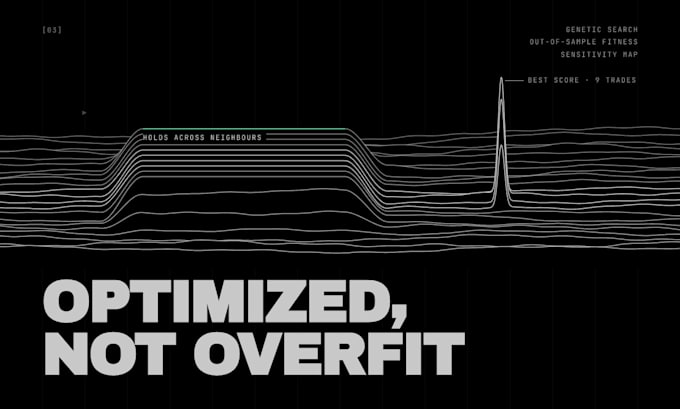
Sensitivity map around the winner a flat plateau is robust, a single bright cell is luck
Before/after table on data the search never saw, with the trade count beside every metric
Updated strategy file in your format, PDF report and the raw run data
Why me
I built Entropable, a quant platform with a DEAP genetic-algorithm optimizer, walk-forward fitness and a CPCV validator. Your strategy runs through the same engine.
How it works
1. Send your rules plus the parameters you want searched, with a plausible range for each
2. I confirm the encoded logic and the risk limits before anything runs
3. Search, validation, report and a short debrief
Not included: writing a strategy for you, live trading, exchange connections.
No financial advice, no signals,

Platform:
TradingView
•
MT5
•
Binance
What if the optimizer finds something that only worked by luck?
Then the report says so. On the sample run in my gallery the winner scored a 9.19 Sharpe in-sample on nine trades — and nine trades cannot support that number. The before/after table puts the trade count next to every metric for exactly this reason. A result I cannot defend is reported as one.